Piloting innovative solutions for climate resilience

Climate-related disasters are a growing threat to European life. It is widely known that physical and organisational measures, such as new flood barriers or emergency plans, can help Europe adapt to these emerging challenges. Innovative solutions in insurance and finance can also encourage proactive adaptation, making individuals and society more resilient for the future. Yet these solutions are less developed. “Financial strategies are less visible and often more complex, and developing them requires knowledge of climate hazards, exposure, vulnerability, loss and damage, and the ways in which risks affect households, infrastructure, businesses and public finances,” explains Hilppa Gregow, research professor at the Finnish Meteorological Institute(opens in new window), adjunct professor at the University of Eastern Finland(opens in new window) and PIISA(opens in new window) project coordinator. “Insurance solutions require a regulatory environment that allows new products,” she adds. Through the EU-funded PIISA project, Gregow and her team developed new solutions to incentivise new adaptive measures, which were then successfully tested in real-world demonstrations in eight European countries. With a focus on solutions across agriculture, forestry and urban resilience, PIISA’s consortium of 12 partners pioneered climate-resilient insurance portfolios to protect communities from floods, droughts, wildfires and storms.
Testing practical climate solutions in European pilots
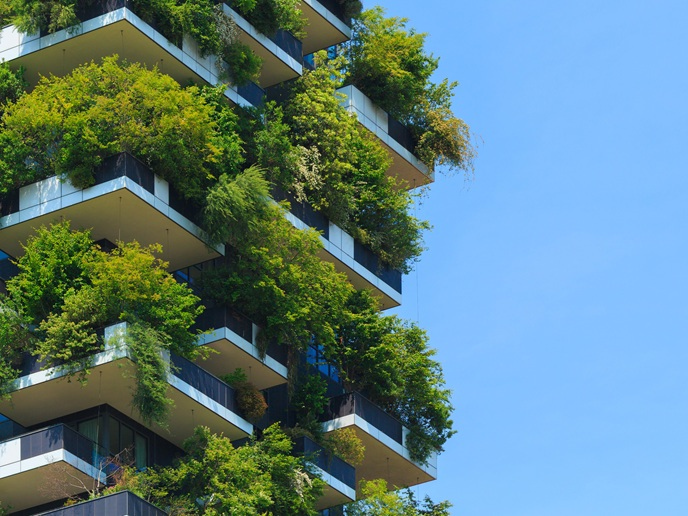
Drawing on her earlier work on innovative climate services and impact outlook development, Gregow designed the PIISA process around three loops of maturity: exploring relatively mature cases; testing with new target groups and regions; and pilot demonstrations. These real-world demonstrations included one in collaboration with Portuguese authorities and local stakeholders, which connected climate and fire-spread simulations with concrete adaptation measures such as fuel breaks. “The results showed that properly implemented and maintained adaptation measures could substantially reduce both wildfire risk and indicative insurance premiums,” notes Gregow. In another pilot, AXA Climate’s(opens in new window) team worked with forest owners and commercial insurance partners in Germany to create a scalable, climate-sensitive framework for windstorm insurance. The core innovation was the Wind Power Exposure Index, which combines wind characteristics with a forest vulnerability map. The framework was tested in Ireland using data from the record-breaking Storm Éowyn of January 2025 and further validated in Denmark, France and Scotland. In the Netherlands, VU Amsterdam(opens in new window) led a green-roof pilot, while Climate Adaptation Services(opens in new window) developed supporting adaptation services. Led by the Barcelona Supercomputing Center(opens in new window), an agricultural pilot in Finland, Italy and Spain combined farmer engagement, climate indicators, seasonal forecasts and index-based insurance design. The Sustainable Finance Observatory(opens in new window) led a pilot in France, pioneering a tool that helps homeowners understand the financial and insurance risks caused by drought-related soil movement. “In Italy, we also received exceptionally strong support from insurance companies,” says Gregow.
Guiding Europe towards a proactive approach to climate risks
Beyond individual pilot successes, the project produced multiple key deliverables. These include: a market review assessing climate awareness and perceptions among European citizens; 10 climate risk indicators that were integrated into the European Commission’s Joint Research Centre ‘Risk Data Hub’; several research articles and joint webinars; a policy brief; and a white paper with recommendations for the insurance sector. PIISA results can guide Europe to move from reacting to climate-related losses towards anticipating and reducing risks, remarks Gregow. “As climate change accelerates, neither public funding nor insurance will be able to cover every loss,” she explains. “Financial protection must therefore be treated as a strategic component of resilience, not as a technical afterthought.”